August 26, 2026
The Retirement Mistake Nobody Warns You About: Dying With Too Much Left Over
One of the risks of retirement is running out of money. This article is about the opposite mistake, working and saving for years longer than a plan actually required, and ending up with a large pile of unspent money at the end. It does not feel like a mistake at the time. It feels responsible. The point of this article is not "stop working the moment your calculator says you're fine," and it is not "always work one more year to be safe" either. It is that a single pass/fail number can't tell you which of those is true for your own plan, and most people never get shown enough information to check.
Rich, Broke, or Just Right
A retirement projection doesn't predict one future. It tests your plan against a thousand different possible sequences of market returns, a crash right after retirement, a decade of flat returns, an ordinary year, a great decade. Every one of those sequences ends in one of three ways. Broke means the money ran out before the plan ended. Spent about right means the balance landed close to zero on schedule. Rich means the household ended up with meaningfully more than they started retirement with.
Here's the plan those numbers came from, run through ThunderHarbor's Risk Analysis.
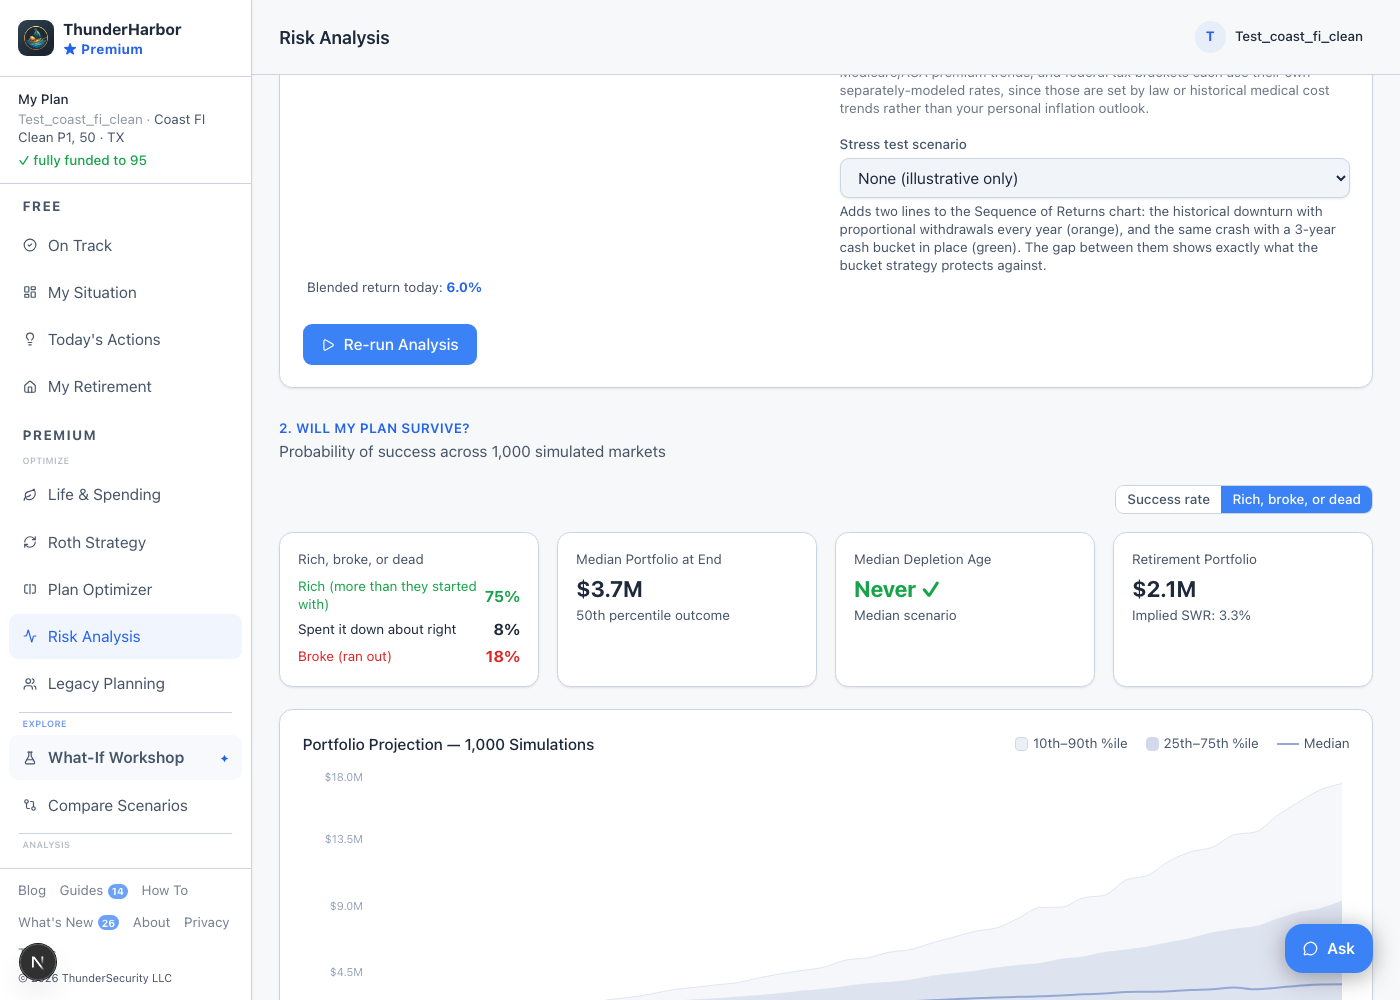
Rich is the largest bucket here, and that's not a coincidence specific to this one plan. A withdrawal amount has to be small enough to survive the worst sequences a thousand simulated markets can throw at it. Bad sequences are the minority, since markets rise more years than they fall. So in every sequence that isn't one of those rare bad ones, the same spending compounds instead of running low. A plan sized to survive the worst case usually overshoots in every other case, which is most of them.
A plain success rate folds Rich and Spent-about-right together into one pass number, 82% here, and stops there. It never shows that three out of every four simulated futures for this exact plan end with millions of dollars unused, or that saving longer to push that 82% higher would mostly widen an already-large surplus rather than closing the gap on the 19% that go Broke.
Why This Is Easy to Miss
Very few people set out to over-save on purpose. It happens gradually. Running out of money in your 80s is a vivid, frightening image. Having saved more than needed is invisible by comparison, a trip not taken, time with family not spent while everyone was healthy enough to enjoy it, a few extra years at a job you were ready to leave. One risk is easy to picture. The other doesn't feel like a risk at all. It feels like prudence, right up until it's the reason for years worked that didn't need to be worked.
The tools most people use to check their plan reinforce this. A single success percentage rewards caution and never charges anything for having too much of it. There's no equivalent number warning "you may have saved more than you needed," so the mistake stays invisible even to people making it.
What to Check in Your Own Plan
"Broke" and "Rich" are not single causes each. A handful of different things can push a plan toward either one, and they call for different fixes, so the useful question isn't "which bucket am I in," it's "which specific lever put me there."
A plan tends to land in Broke for one of a few reasons. Spending is set higher than the portfolio and any guaranteed income can support together. Retirement started before savings actually caught up to that spending level. A bad run of returns hit early, a market drop in the first few years of withdrawals does more lasting damage than the same drop hitting later, since there's less time left for the portfolio to recover. Or the inflation rate used for planning is lower than how spending has actually grown, which quietly erodes the plan's cushion every year without ever showing up as one dramatic event.
A plan tends to land in Rich for a different, easier to overlook set of reasons. Social Security, and a pension if there is one, may already cover most of a typical year's spending on their own, so the portfolio barely gets touched and grows on dividends and returns instead of shrinking. The spending figure driving the whole plan might still be a conservative estimate from years ago that was never checked against what actually gets spent today. A strong run of market returns, or dividend income higher than assumed, can do the same thing from the other direction. Or the return and inflation assumptions behind the plan are deliberately cautious, reasonable on their own, but that means the simulation is testing against a harder world than the one that usually shows up.
Finding out which of these applies means looking at each lever on its own instead of just the pass/fail headline. How much of a typical year's spending is already covered by Social Security and pension income before the portfolio gets touched at all. Whether the spending number in the plan matches what actually gets spent now, not an old guess. What return and inflation rate the projection assumes, and how conservative that is against history. If Broke is the dominant bucket, changing spending, retirement age, and return assumptions one at a time, instead of all at once, shows which one is actually doing the damage.
Where a Real Surplus Should Go
Once Rich looks like a real pattern and not a rounding accident, the next question is what to actually do with the surplus, and the honest answer depends on which account it sits in and what the goal is.
A surplus sitting in a traditional 401(k) or IRA is still fully taxable whenever it comes out, whether that's required minimum distributions during your own life or a beneficiary spending it down under the 10-year rule after you're gone. If the money is clearly more than will be spent, converting some of it to Roth while still in a lower bracket, before RMDs force larger withdrawals into a possibly higher one, moves that same balance into an account nobody, including an heir, ever owes tax on again.
If leaving money to charity is part of the picture, a traditional account is often the better one to earmark for that, since a charity owes no tax on it either way, while a person inheriting it does. That points toward leaving tax-free or already-taxed money to people and traditional balances to causes, rather than converting everything or leaving the mix to chance.
None of this is automatic, and it depends heavily on the specifics. Someone planning to spend the surplus themselves doesn't need to convert anything, more spending is the actual fix. Someone with no interest in leaving an inheritance at all might reasonably prefer simplicity over optimizing a tax bill nobody will ever see the benefit of. The point isn't one right answer, it's that a real surplus is worth a deliberate decision about where it ends up, not a default that happened because nobody looked.
Neither Extreme Is the Goal
None of this is an argument for spending recklessly or aiming for a 0% success rate. A real cushion against a bad decade is worth having, and some people genuinely want to leave a large inheritance on purpose, that's a legitimate goal, not a mistake, as long as it's a choice rather than an accident. The point isn't that saving too much is always wrong. It's that most people have no way of knowing they're doing it, because the number they're shown was never built to tell them.
Running out of money is loud and gets all the attention. Dying with too much left over is silent, and costs just as much, paid in years instead of dollars.
Not financial advice
This article is for informational purposes only. Nothing here constitutes financial, tax, or legal advice. The example above is illustrative, not a real household. Past market performance does not guarantee future results. Always consult a qualified professional before making significant financial decisions.
See the whole distribution, not just pass or fail
ThunderHarbor's Risk Analysis runs your real plan through 1,000 simulated markets and shows both sides, how often it fails, and how often it leaves you with far more than you needed.
Start your free plan